The property may require more cash than expected or at a difficult time.
Investment Property Risk Guide
INVESTOR RESOURCES
Investment Property Risk Guide
Risk cannot be removed, but it can be identified, investigated, priced into the decision and managed with clearer limits and contingencies.
FHP field note · reviewed 10 October 2026
Review status: a risk register must change
Likelihood, consequence and controls should be updated when finance, tenant, insurance, building or location evidence changes. A static low-risk label is not acceptable.
- Record the source and review date beside every transaction-specific input.
Primary sources used for this reviewMoneySmart — Property investmentChecked 10 October 2026. Government rules, thresholds and property information can change. Confirm current eligibility and transaction details with the authority, lender and relevant licensed advisers before acting.
Risk becomes manageable only when assigned.
This investment property risk guide resource is an educational framework for recording evidence and preparing questions. It does not recommend a property or replace financial, credit, legal, tax, building or other advice for your circumstances.
Defects, title issues, supply or location factors may affect use, cost or demand.
Incomplete evidence, urgency and optimistic assumptions can weaken otherwise careful research.
Map exposure, controls and contingencies
Finance and cash-flow risk
Rates, lending policies, valuations, income and expenses can change. A plan that only works under today’s best assumptions may have little capacity to absorb ordinary variation.
- Stress-test finance costs and rent.
- Allow for vacancy and irregular expenses.
- Retain an appropriate buffer based on individual advice.
- Understand refinancing and settlement constraints.
Property and construction risk
Established and new properties have different—but real—risks. These may include defects, maintenance, incomplete works, specification changes, delays and uncertainty about what is legally approved.
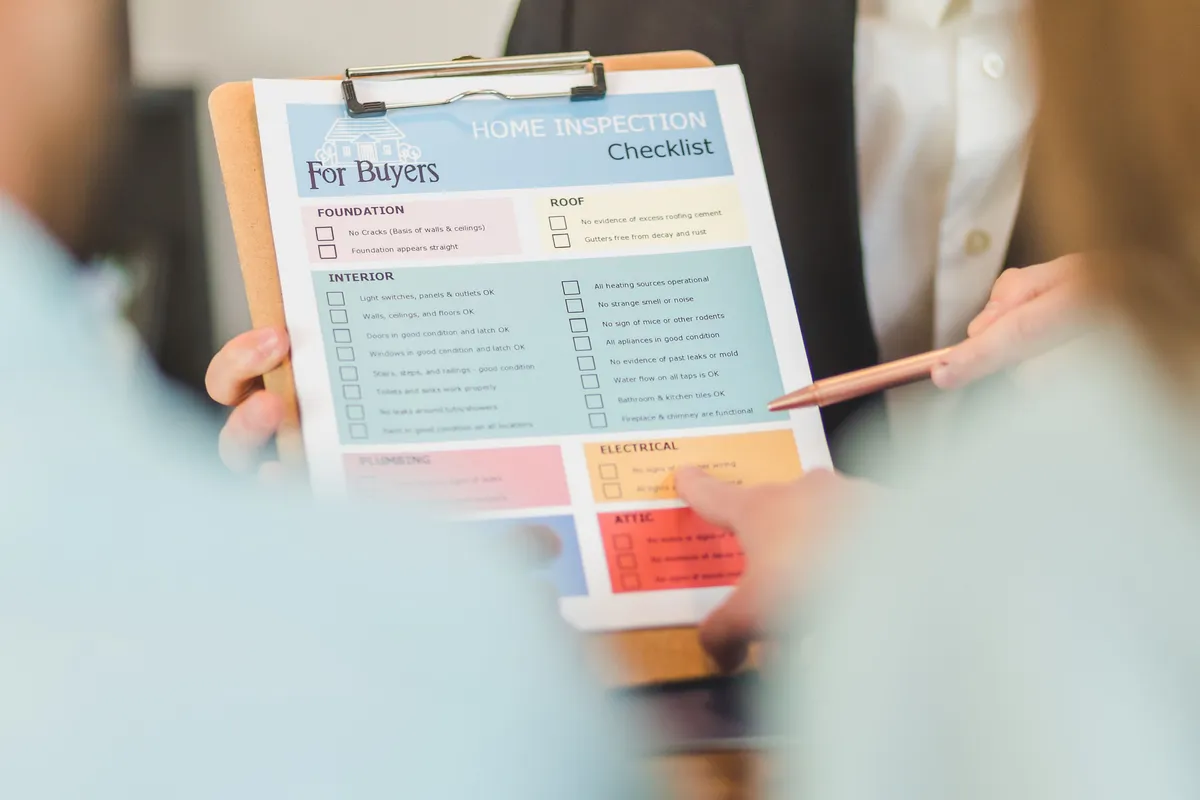
- Use appropriate building, pest or specialist inspections.
- Review plans, inclusions and contracts carefully.
- Research relevant developer or builder information.
- Document unresolved defects and responsibility for rectification.
Location and market risk
Local employment, competing supply, amenity, planning, environmental exposure and buyer or tenant demand can change. A broad city narrative may not describe the property’s immediate market.
- Research at the relevant local level.
- Check current and proposed comparable supply.
- Investigate flood, bushfire and other location-specific considerations.
- Avoid relying on a single forecast or promoter.
Legal, management and liquidity risk
Contracts, title restrictions, strata arrangements, tenancy obligations and management failures can create cost or delay. Property can also take time and money to sell.
- Obtain independent contract and title advice.
- Understand landlord and strata obligations.
- Plan management and insurance before leasing.
- Consider exit costs and timeframes before purchase.
A practical sequence
01
Identify
List risks by finance, income, property, location, legal and management category.
02
Verify
Find evidence and professional input rather than assigning risk from assumptions.
03
Respond
Avoid, reduce, transfer or consciously accept each material risk.
04
Monitor
Review risks during settlement, ownership and major financial or market changes.
Property risk register
Turn a list of concerns into assigned controls.
For each risk, record the evidence, likelihood, consequence, preventive control, contingency, responsible person and next review date. “Aware of risk” is not a treatment.
| Risk | Early evidence | Preventive control | Contingency |
|---|---|---|---|
| Valuation shortfall | Long settlement, incentives, limited comparable sales. | Finance advice, conservative liquidity and valuation timing understood. | Extra-cash limit and legal advice on contract options. |
| Rental underperformance | Wide appraisal range, incentives, competing completions. | Multiple comparables, vacancy allowance and pressure case. | Buffer, pricing response and management plan. |
| Defect or maintenance event | Inspection findings, age, unresolved defects or weak records. | Appropriate reports, quotes, warranties and reserve. | Repair authority, insurance process and liquidity. |
| Supply concentration | Large pipeline of similar stock in the same tenant/buyer segment. | Planning and approvals research at the relevant submarket level. | Longer vacancy/sale-period assumption. |
| Deadline failure | Multiple unresolved conditions close to contract or settlement date. | Responsibility and due-date register. | Escalation path through legal and finance advisers. |
Stop condition: a severe consequence with no workable control or contingency should remain visible even when its estimated likelihood is low.
Official starting points
- MoneySmart: property investment — Australian Government guidance on costs, risk and property-investment decisions.
Investment Property Risk Guide: questions to resolve
Can due diligence remove all risk?
No. It improves information and decision quality but cannot guarantee an outcome.
Is insurance a complete risk solution?
No. Policies have limits, conditions and exclusions, and many risks are not insurable.
What should happen when a critical question remains unanswered?
Treat it as unresolved and understand the consequence before proceeding.
General information only. This page does not provide personal financial, credit, legal, tax or investment advice. Property information, prices, availability, rules and market conditions can change. Verify current information and obtain advice appropriate to your circumstances before making a commitment.
Next evidence for investment property risk guide.
Add the shortlist to a risk register.
Add each shortlisted property to the risk register before deciding whether the controls and contingencies are workable.
Search available properties →